What Is Reinsurance? Definition, Types and How It Works
By Markets & Investing DeskUpdated Nov 10, 2026
Definition
Reinsurance is insurance bought by insurance companies. A primary insurer transfers part of the risk on policies it has written to a reinsurer in exchange for a share of premium.
Key takeaways
- Reinsurance moves part of an insurer's liability to a reinsurer, limiting the insurer's net loss on single large claims and on catastrophes that trigger many claims at once.
- Facultative contracts cover one specific risk; treaty contracts cover a whole class of business over a set period.
- Proportional reinsurance shares premiums and losses by an agreed percentage; non-proportional reinsurance pays only after losses exceed a set retention.
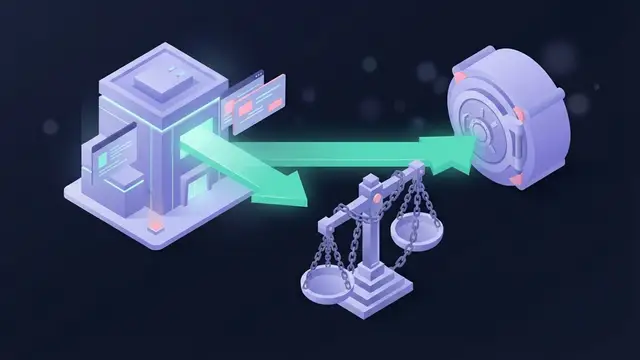
Reinsurance is insurance bought by insurance companies. Under a reinsurance contract, a primary insurer (the ceding company or cedent) transfers part of the risk from policies it has written to another company (the reinsurer) in exchange for a share of premium. If covered claims arrive, the reinsurer reimburses the cedent for its agreed portion. The original policyholders usually never deal with the reinsurer. Their contract remains with the insurer that sold the policy.
How Reinsurance Works
The cedent decides how much of each risk it wants to keep. That kept portion is its retention (also called the priority). Everything above it, up to an agreed limit, is ceded to the reinsurer. The reinsurer earns premium for accepting that exposure and pays its share when covered losses occur.
Reinsurers spread risk too. When a reinsurer passes part of its own assumed risk to yet another reinsurer, the transaction is called retrocession, and the company taking it on is the retrocessionaire. This chain lets very large exposures, such as a major hurricane or earthquake, be shared across many balance sheets.
Facultative vs. treaty
Facultative reinsurance covers an individual risk or policy. Each one is offered and negotiated on its own, and the reinsurer is free to accept or decline. It is typically used for high-value or unusually hazardous risks, such as a hospital or a large industrial plant, that fall outside what a treaty will accept.
Treaty reinsurance covers a defined book of business, such as all of an insurer’s auto policies, for a fixed period. Policies that fit the treaty terms are covered automatically, without case-by-case approval.
Proportional vs. non-proportional
Under proportional reinsurance, the reinsurer takes an agreed share of premiums and pays the same share of losses. In a quota share arrangement, that percentage is fixed across all covered policies. In a surplus arrangement, the insurer keeps each risk up to a set amount and cedes the portion above it, so the ceded share varies by policy size. The reinsurer usually pays the cedent a ceding commission to cover acquisition, underwriting and administrative costs of writing the business.
Under non-proportional reinsurance, there is no fixed share of premiums or losses. The reinsurer pays only when losses exceed the retention. The main form is excess of loss, which can apply per risk, per occurrence (one event, such as a single storm) or on an aggregate basis (cumulative losses over a period). Catastrophe programs are usually built this way.
Timing of coverage
Contracts also define which losses fall inside the coverage period. A risk-attaching contract covers losses on policies that begin during the contract term, even if the loss happens after the reinsurance contract ends. A losses-occurring contract covers losses that happen during the term, regardless of when the underlying policy started.
Example of Reinsurance
Hypothetical figures, for illustration only.
An insurer writes a commercial property policy with a $10 million limit and collects $200,000 in premium.
Quota share at 40%: the insurer cedes $80,000 of premium (less any ceding commission it receives back). A $5 million claim is split $3 million to the insurer and $2 million to the reinsurer.
Excess of loss, $2 million retention, $8 million limit: the insurer pays the first $2 million of any covered loss. On the same $5 million claim, the insurer pays $2 million and the reinsurer pays $3 million. On a $1.5 million claim, the reinsurer pays nothing, because the loss never reaches the retention.
Why Is Reinsurance Important?
Insurers must hold reserves sufficient to pay claims on the policies they issue. Reinsurance reduces the net liability those reserves must support, which serves several purposes:
- Capacity: the insurer can write more policies, or larger ones, without raising equivalent new capital.
- Catastrophe protection: losses from a single event that hits many policyholders are capped at the retention.
- Stable results: large swings in annual losses are smoothed, making earnings and solvency more predictable.
- Financing: ceding commissions and reinsurer payments give the cedent liquidity when exceptional losses arrive.
- Expertise: reinsurers see risks across many markets and can support pricing and underwriting of unfamiliar lines.
Limitations of Reinsurance
- Cost: ceded premium is revenue the insurer gives up. Protection against rare events reduces profit in years without them.
- Counterparty risk: if a reinsurer cannot or will not pay, the cedent still owes its policyholders in full. Contracts may include insolvency clauses defining what happens if either party fails.
- Disputes: treaty wording on events, timing and exclusions can be complex, and disagreements over whether a loss is covered can delay recoveries.
- Availability: reinsurance terms are negotiated, and after heavy catastrophe losses, coverage can become more expensive or harder to buy.
Reinsurance vs. Related Terms
Coinsurance usually refers to a policyholder sharing a percentage of covered costs with the insurer, or several insurers each directly covering part of one risk, with each having a contract with the insured. In reinsurance, only the primary insurer contracts with the insured.
FAQs
Do life and health insurers use reinsurance?
Yes. Reinsurance applies across life, health, property and casualty lines. Life insurers commonly cede part of large individual policies above their retention, using the same proportional and non-proportional structures described above.
The Bottom Line
Reinsurance matters to insurers managing reserves and catastrophe exposure, and to policyholders whose contracts stay with the original insurer. It lets insurers write more business, cap losses from single events and stabilize results. The protection has limits: ceded premium reduces profit, terms can tighten after heavy losses, and the cedent still owes policyholders in full if a reinsurer fails to pay.